
Debt Has a Direction
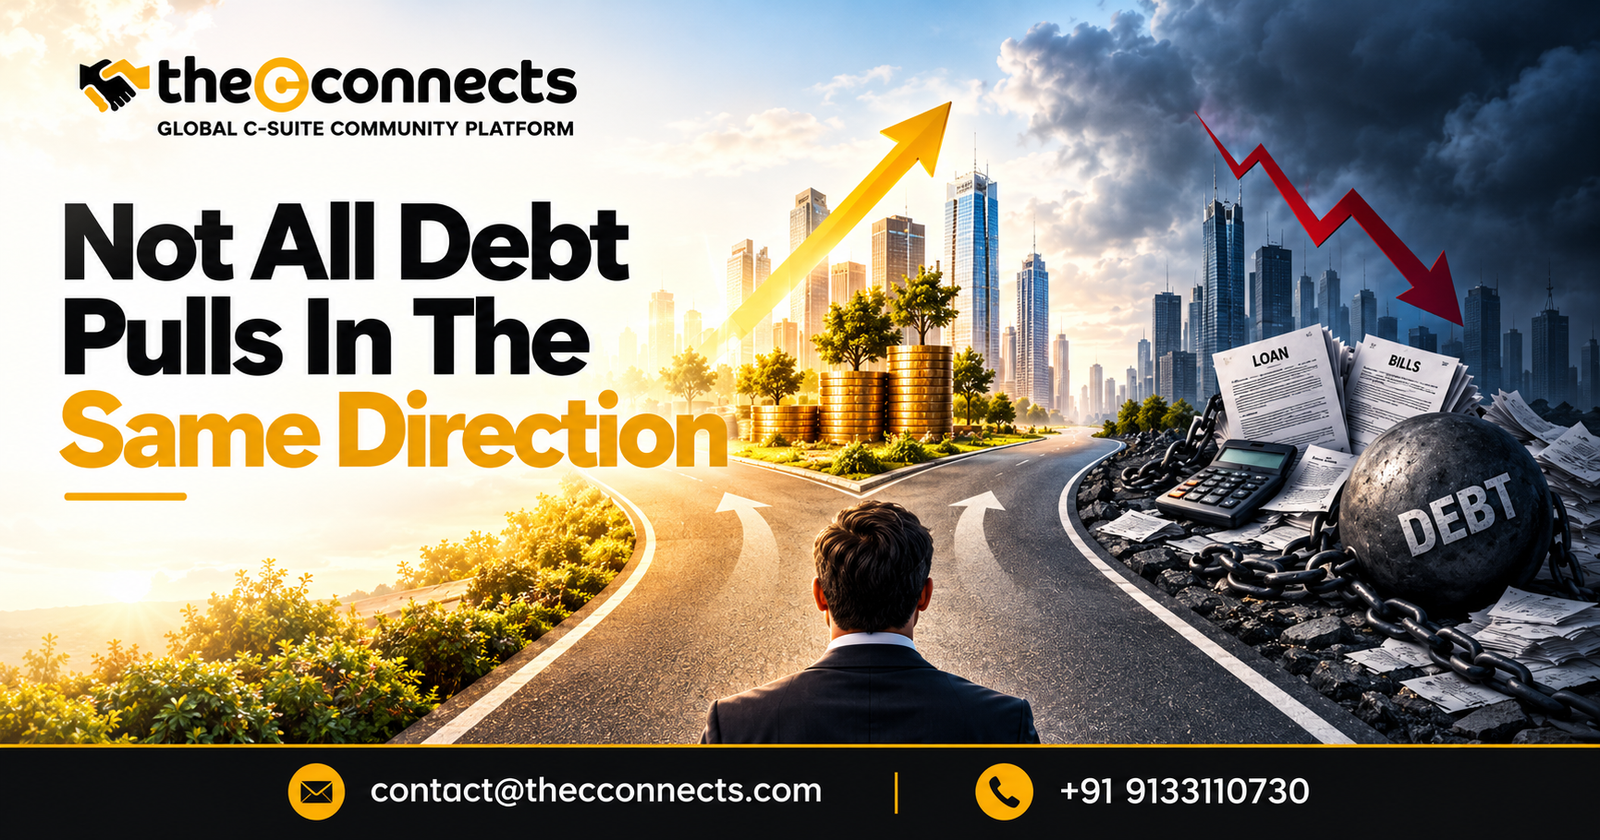
Most people talk about debt like it is a personality flaw or a financial emergency waiting to happen. That view is understandable, especially if you have ever watched a balance grow faster than your paycheck. But debt is not one thing. It behaves more like a force. It pushes, pulls, accelerates, or drags, depending on what it is attached to.
That is why conversations about debt often feel incomplete. A family trying to get breathing room through National Debt Relief is dealing with a very different kind of pressure than a person using a loan to finish a degree or expand a business. Both situations involve borrowing. Only one tells you whether that borrowing is moving life forward or pulling it off course.
Think of Debt Like a Tow Rope
A tow rope can rescue a stuck car or yank it deeper into a ditch. Debt works the same way. The key question is not just, “How much do I owe?” It is, “What is this debt helping me build, and what is it costing me while I carry it?”
Some debt creates options. A mortgage can turn monthly housing costs into ownership over time. A student loan can raise earning potential, though only if the degree and repayment plan make sense. The U.S. Department of Education lays out several federal student loan repayment paths, which shows just how much the long term cost depends on structure, not just the original amount borrowed; federal student loan repayment options.
Other debt quietly drains momentum. High interest credit card balances used for everyday overspending often do not build anything lasting. Buy now, pay later habits can feel harmless in the moment, but stacking short term obligations can reduce cash flow for months. Debt that funds consumption without improving income, stability, or asset growth tends to pull backward.
The Real Divide Is Productive Versus Extractive
A more useful way to sort debt is by what it does after the purchase is over.
Productive debt supports something that can appreciate, generate income, reduce future costs, or strengthen your financial position over time. That does not guarantee success, but it creates the possibility of return. A reasonable small business loan used for equipment, inventory, or expansion may increase revenue. A mortgage may build equity. A carefully chosen certification program may open the door to higher pay.
Extractive debt does the opposite. It keeps taking after the initial benefit is gone. You enjoyed the vacation, the impulse purchase, or the convenience, but the bill keeps collecting interest long after the excitement fades. In that case, debt is not acting like a bridge. It is acting like a tax on your future earnings.
This lens changes the conversation. Instead of labeling all debt as good or bad, you start asking whether it produces value greater than its cost.
Time Magnifies Whatever Direction Debt Is Already Pulling
Debt rarely stays small in its effects. Time exaggerates its direction.
If a loan is tied to an appreciating asset or stronger earning power, time may work in your favor. If a balance carries high interest and no lasting benefit, time turns inconvenience into strain. The same month that looks manageable today can look suffocating a year from now.
That is why interest rate matters so much, but so does opportunity cost. Money used to service unhelpful debt is money that cannot go toward savings, retirement, emergencies, or better opportunities. The Securities and Exchange Commission explains the mechanics behind compounding clearly, and those same principles that help investments grow can make expensive debt much harder to outrun: how compound interest works.
In other words, debt always asks for more than the payment amount. It also asks what you are giving up by carrying it.
Emotional Relief Can Hide Financial Direction
Here is where many people get tripped up. Debt that feels helpful is not always helpful. Debt that feels scary is not always harmful.
Financing a purchase can create immediate relief. It solves the problem right now. That emotional ease can make a bad deal look reasonable. On the other hand, a large but structured debt with a clear payoff path can feel intimidating even when it is serving a useful purpose.
This is why monthly payment thinking can be dangerous. When people shop based only on whether they can “fit the payment in,” they stop evaluating the total cost, the interest, and the long term tradeoff. A lower monthly payment can simply mean a longer stretch of financial drag.
A better question is this: after this debt enters my life, will my future self have more choices or fewer?
Healthy Debt Still Needs Guardrails
Even debt with a strong purpose can turn against you if the terms are poor. A mortgage that stretches your budget too thin can create constant instability. A business loan taken without realistic cash flow planning can become a source of panic. Student loans for a program with weak job prospects may not deliver the lift you expected.
That is why the details matter. Interest rate, repayment term, flexibility, and risk all shape direction. Productive debt usually has a plan behind it. Extractive debt often starts with urgency, optimism, or convenience and ends with surprise.
It also helps to remember that debt should not be your only tool. Savings, patience, negotiation, and delayed gratification may move slower, but they often preserve freedom. Borrowing is powerful precisely because it speeds things up. Speed is useful only when you are headed somewhere worthwhile.
Debt Is Best Measured by What It Leaves Behind
When the spending is done and the statements keep arriving, what remains? An asset? A credential? A stronger income stream? More stability? Or just less room in your budget?
That question cuts through almost every debt decision. Not all debt pulls in the same direction because not all debt leaves the same footprint. Some debt leaves behind leverage. Some leaves behind weight.
The smartest borrowers are not the people who avoid every loan. They are the people who understand the difference between borrowing to build and borrowing to maintain a lifestyle they cannot actually afford. Once you see debt as a directional force, better choices become easier to spot.
Debt is never neutral. It is either helping carry you somewhere better, or asking you to carry it.